Simply Solar Loan: The Ultimate Solar Financing Solution

Simply Solar Loan: The Ultimate Solar Financing Solution 🌞


Electric bills are doubling, insurance costs are rising, and mortgage rates remain high—but there’s one bright spot: solar energy. Whether you’re looking for a solar-specific loan, leveraging your home equity, or exploring other financing options, we’ve got you covered. Let’s take a closer look at the Simply Solar Loan and compare it to other popular financing choices.


Simply Solar Loan: Perfect for Going Green

  • Earn Big with Borrower Incentives: Receive 3.5% of your home’s sales price, up to $13,000, as a cashback reward for choosing solar energy.
  • Flexible Financing Options: Finance up to 20% of your home’s value to cover the cost of your solar system.
  • FHA Solar and Wind Technologies Integration: Includes the FHA Solar and Wind Technologies Loan, making solar panel installation seamless and efficient.
  • Tax Savings: Take advantage of the 30% Federal Solar Tax Credit, significantly reducing the overall cost of your solar system.
  • Educational Support: Access homebuyer education and financial mentoring to make informed decisions about energy efficiency.
  • Long-Term Energy Savings: Reduce energy costs, increase your home’s value, and enjoy the benefits of energy-efficient upgrades.
  • Competitive Rates and Streamlined Approval: Attractive interest rates and a quick, easy approval process get you started with solar energy sooner.


Simply Solar is the ideal choice for homeowners looking for a loan tailored specifically for solar energy, packed with financial incentives and sustainability-focused benefits.


Home Equity Line of Credit (HELOC): Flexibility with Lower Rates

If you’ve built equity in your home, a HELOC can be a great way to finance your solar system.

  • Lower Interest Rates: HELOCs often come with lower rates compared to other loan options because they’re secured by your home.
  • Versatile Use: While you can use funds for solar, a HELOC also allows you to fund other home improvement projects.
  • Tax Benefits: Depending on your situation, you may be able to deduct interest payments if the funds are used for home improvements.*
  • Flexible Borrowing: Borrow only what you need, when you need it, and pay it back over time.

A HELOC is ideal if you want flexibility and are looking to finance additional projects beyond solar.


Personal or Home Improvement Loans: Quick and Unsecured

For homeowners who prefer not to use their home as collateral, personal loans offer a straightforward financing option.

  • Quick and Easy Approval: Access funds faster than other loan options.
  • No Collateral Needed: These loans don’t require you to tap into your home equity.
  • Fixed Interest Rates: Enjoy predictable monthly payments for easier budgeting.
  • Shorter Terms: Pay off your loan faster with shorter repayment periods.

This is a solid choice for homeowners without equity or those who want a simpler, unsecured financing option.


Why Go Solar Now?

With energy costs rising and financial incentives at an all-time high, there’s no better time to invest in solar energy. Solar power helps you:

  • Lower Energy Bills: Reduce your monthly utility costs and shield yourself from future rate hikes.=
  • Increase Home Value: Homes with solar systems are in demand and can sell for more.
  • Reduce Your Carbon Footprint: Make an eco-friendly impact while saving money.
  • Take Advantage of Incentives: Programs like the Simply Solar Loan and federal tax credits make solar more affordable than ever.


Which Financing Option Is Right for You?

  • Choose the Simply Solar Loan if you want a program tailored for solar energy, complete with cashback rewards and solar-specific features.
  • Go with a HELOC if you want low rates, flexibility, and the ability to fund other projects alongside solar.
  • Opt for a Personal Loan if you don’t want to tap into your home equity or need quick access to funds without collateral.


Take the Next Step Toward Energy Independence

Whether you’re upgrading your home or planning for a greener future, there’s a financing option that fits your goals. Our team is here to help you find the best solution for your budget and energy needs.


Contact us today to learn more about Simply Solar, HELOCs, or other financing options, and start your journey toward clean, renewable energy!

📩 DM me or click here to schedule your free consultation today! https://freshhomeloan.com/schedule-a-meeting/
Garick Werdmuller
garrick@freshhomeloan.com
1151 Harbor Bay Parkway Suite 136
Alameda CA 94502
(510) 282-5456


Socials:
https://www.facebook.com/freshhomeloan/
https://www.linkedin.com/in/garrick-werdmuller-b044253/
https://www.youtube.com/@freshhomeloan-garrickwerdm316


All loan approvals are conditional and not guaranteed and subject to lender review of all information. Loan is conditionally approved when lender has issued approval in writing, but until all conditions are met, loan cannot be funded. Specified rates and [products may not be available to all borrowers. Rates subject to change according to market conditions and agreed upon lock times set by borrower. Fresh Home Loan Inc. is an Equal Opportunity Mortgage Broker in California. This licensee is performing acts for which a real estate license is required. Fresh Home Loan, Inc. is licensed by the California Department of Real Estate #02137513 NMLS # 2124104


#Mortgage #RealEstateInvesting #PropertyInvestment #DelayedFinancing #CashOutRefinance #RealEstateFinance #InvestorFinancing #FlexibleFinancing #FirstTimeHomeBuyer #RealEstateInvestors #FreshHomeLoan #CaliforniaRealEstate

By Garrick Werdmuller • October 5, 2026
Win more listings by showing sellers the value of your local expertise.
By Garrick Werdmuller • October 1, 2026
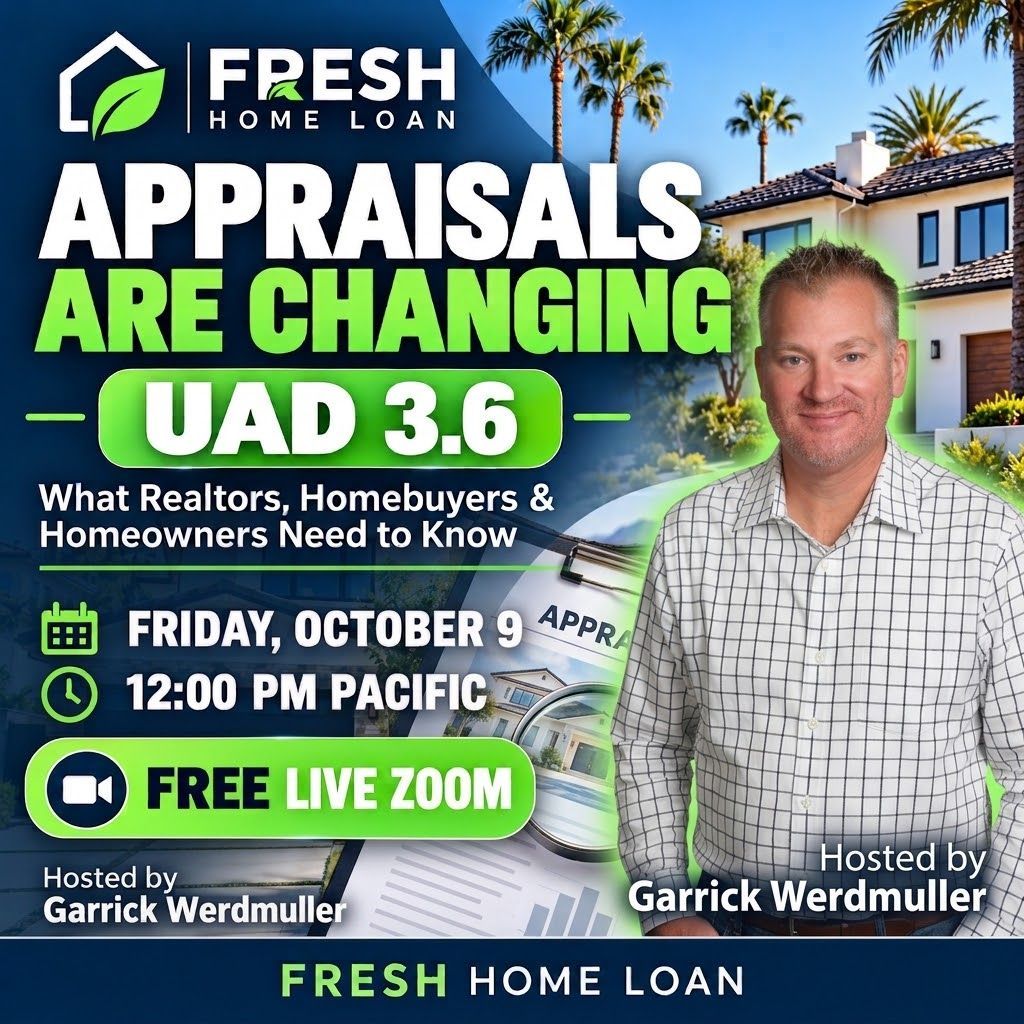
Join me for a FREE live Zoom presentation about the new appraisal reporting standard and how to prepare for your next purchase, sale, or refinance.
By Garrick Werdmuller • September 30, 2026
New Title
By Garrick Werdmuller • September 17, 2026
Thinking about buying a home while mortgage rates are high? Learn how less competition, seller credits and negotiating power could save you money.
By Garrick Werdmuller • August 20, 2026
Looking to Consolidate Debt and do some Home Improvement? Got a “COVID Mortgage Rate”? Don’t Touch It!!!
By Garrick Werdmuller • August 11, 2026
Para muchos propietarios de 62 años o más , una hipoteca inversa puede ser mucho más que un préstamo: puede ser una poderosa herramienta de planificación financiera. Después de pasar décadas acumulando capital en una vivienda, muchos jubilados descubren que una parte importante de su patrimonio está concentrada en su propiedad. Una hipoteca inversa puede ayudar a aprovechar parte de ese capital y convertirlo en fondos disponibles, al mismo tiempo que permite a los propietarios continuar viviendo en la casa que aman. Aunque una hipoteca inversa no es adecuada para todos, puede ofrecer beneficios importantes para el prestatario adecuado. A continuación, presentamos cinco razones por las que vale la pena considerar una hipoteca inversa. 1. Generar Ingresos Adicionales Durante la Jubilación La jubilación suele implicar un cambio importante en el estilo de vida. Aunque los años de trabajo hayan quedado atrás, los gastos mensuales no desaparecen. Para muchos jubilados, una hipoteca inversa puede ayudar a cerrar la brecha entre los ingresos de jubilación y los gastos cotidianos. Los fondos recibidos de una hipoteca inversa pueden utilizarse para: Complementar los ingresos de jubilación Cubrir gastos del hogar Crear una red de seguridad financiera Mejorar el flujo de efectivo durante la jubilación Debido a que los fondos de una hipoteca inversa son dinero proveniente de un préstamo y no ingresos obtenidos por trabajo, generalmente no se consideran ingresos sujetos a impuestos. Para los propietarios que cuentan con un capital considerable en su vivienda, pero tienen activos líquidos limitados, una hipoteca inversa puede proporcionar una valiosa flexibilidad financiera. 2. Acceder al Capital de tu Vivienda de la Manera que Mejor se Adapte a Ti Una de las principales ventajas de una hipoteca inversa es la flexibilidad. Dependiendo del programa, los propietarios pueden elegir recibir los fondos como: Una suma global Pagos mensuales Una línea de crédito Una combinación de diferentes opciones de pago Esta flexibilidad permite adaptar el préstamo de acuerdo con los objetivos financieros y las necesidades de jubilación de cada propietario. Ya sea que necesites ingresos mensuales constantes o acceso ocasional a fondos, una hipoteca inversa puede estructurarse para adaptarse a tu situación. 3. Eliminar los Pagos de una Hipoteca Existente Muchos propietarios utilizan una hipoteca inversa para liquidar una hipoteca tradicional existente. Al eliminar un pago hipotecario mensual, los jubilados pueden mejorar significativamente su flujo de efectivo mensual. Para los propietarios que viven con ingresos fijos durante la jubilación, eliminar uno de sus gastos mensuales más importantes puede hacer que administrar el presupuesto sea mucho más sencillo. Aunque los prestatarios deben continuar pagando los impuestos sobre la propiedad, el seguro de vivienda y mantener la propiedad en buenas condiciones, eliminar un pago hipotecario mensual puede proporcionar un alivio financiero considerable. 4. Ayudar a Cubrir Gastos Inesperados La vida está llena de imprevistos, y algunos de los más costosos pueden estar relacionados con gastos médicos, reparaciones del hogar o emergencias familiares. Una hipoteca inversa puede proporcionar acceso a fondos cuando más se necesitan. Muchos propietarios utilizan los fondos de una hipoteca inversa para: Pagar gastos médicos Financiar modificaciones en la vivienda Cubrir costos de cuidados a largo plazo Realizar reparaciones importantes Crear un fondo para emergencias Tener acceso al capital acumulado en la vivienda puede ayudar a los jubilados a evitar depender de tarjetas de crédito con altas tasas de interés, préstamos personales o retirar fondos adicionales de sus cuentas de jubilación durante momentos difíciles. 5. Protección Incorporada Mediante un Préstamo Sin Recurso Una de las protecciones más importantes para los consumidores de las hipotecas inversas asegurad as por la FHA es que son préstamos sin recurso (non-recourse loans). Esto significa que ni el prestatario ni sus herederos deberán pagar más que el valor de la vivienda cuando el préstamo llegue a su vencimiento y sea exigible. Si eventualmente el saldo del préstamo supera el valor de la vivienda, el seguro hipotecario de la FHA cubre la diferencia. Esta protección puede brindar tranquilidad tanto a los propietarios como a sus familias, especialmente durante períodos de incertidumbre en el mercado inmobiliario. ¿Es una Hipoteca Inversa Adecuada para Ti? Una hipoteca inversa no se trata simplemente de pedir dinero prestado: se trata d e crear opciones. Para algunos propietarios, puede ayudar a mejorar el flujo de efectivo durante la jubilación, eliminar pagos hipotecarios mensuales, preservar cuentas de inversión y proporcionar una mayor seguridad financiera. La clave está en comprender cómo funciona el programa y evaluar si se alinea con tus objetivos a largo plazo. La situación de cada propietario es diferente. Por eso, hablar con un especialista experimentado en hipotecas inversas puede ayudarte a determinar si una hipoteca inversa es una buena opción para tu estrategia de jubilación. Reflexiones Finales Para los propietarios que cumplen con los requisitos, una hipoteca inversa puede ser una forma valiosa d e poner el capital acumulado en su vivienda a trabajar, sin tener que venderla ni asumir un pago hipotecario mensual obligatorio. Cuando se utiliza de manera estratégica, puede ayudar a crear flexibilidad, reducir el estrés financiero y proporcionar recursos adicionales durante la jubilación. Las mejores herramientas financieras son aquellas que respaldan tus objetivos y, para muchos jubilados, una hipoteca inversa puede ser una de ellas. Agenda una Consulta Contacta a Fresh Home Loan hoy mismo para analizar tus opciones con un profesional hipotecario con experiencia. https://freshhomeloan.com/schedule-a-meeting/ Garrick Werdmuller President & CEO Fresh Home Loan Inc. 510-282-5456 NMLS 242952 Diana Diaz Operations Manager 510-751-0303 customercare@freshomeloan.com Síguenos en redes sociales: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@FreshHomeLoan https://www.tiktok.com/@freshhomeloan Todas las aprobaciones de préstamos están sujetas a revisión y aprobación final por parte del prestamista. Los préstamos se consideran aprobados únicamente cuando se emiten por escrito y se cumplen todas las condiciones. Las tasas y productos pueden no estar disponibles para todos los prestatarios y están sujetos a cambios según las condiciones del mercado y los términos de bloqueo de tasa. Fresh Home Loan Inc. es un Mortgage Broker de Igualdad de Oportunidades en California. Esta compañía realiza actos que requieren licencia de bienes raíces. Fresh Home Loan, Inc. está licenciada por el California Department of Real Estate #02137513 | NMLS #2124104. #HipotecaInversa #HECM #PlanificacionParaLaJubilacion #CapitalDeVivienda #PropietariosDeVivienda #IngresosDeJubilacion #AsesorHipotecario #PlanificacionFinanciera #PropiedadDeVivienda #FreshHomeLoan #BienesRaices #LibertadFinanciera 
By Garrick Werdmuller • August 11, 2026
Aunque tanto un HELOC como un HELOAN permiten a los propietarios acceder al capital acumulado en su propiedad sin tener que refinanciar su primera hipoteca existente, están diseñados para diferentes necesidades financieras. ¿Qué es un HELOC? Una Home Equity Line of Credit (HELOC), o línea de crédito sobre el valor acumulado de la vivienda, es una línea de crédito renovable respaldada por el capital de su propiedad. Puede considerarse similar a una tarjeta de crédito, pero generalmente con una tasa de interés mucho más baja porque está respaldada por su vivienda. En lugar de recibir todos los fondos de una sola vez, usted obtiene la aprobación para un límite máximo de crédito y puede retirar dinero según lo necesite durante el período de disposición. Esta flexibilidad hace que un HELOC sea particularmente atractivo para propietarios que tienen gastos continuos o cuyos costos aún no están completamente definidos. Por ejemplo, si está remodelando una cocina, construyendo una ADU (Accessory Dwelling Unit), pagando la matrícula universitaria durante varios semestres o simplemente quiere tener acceso a fondos para futuras oportunidades, un HELOC le permite pedir prestado únicamente lo que necesita y cuando lo necesita. En muchos casos, los propietarios pagan intereses solamente sobre la cantidad que realmente han utilizado, y no sobre el total de la línea de crédito aprobada. Un HELOC también puede funcionar como una red de seguridad financiera. Muchos propietarios establecen un HELOC y mantienen los fondos disponibles para emergencias, oportunidades de inversión o gastos inesperados. Debido a que el dinero está disponible cuando se necesita, ofrece una flexibilidad que un préstamo tradicional de suma global no puede proporcionar. ¿Qué es un HELOAN? Un Home Equity Loan (HELOAN), o préstamo sobre el valor acumulado de la vivienda, es una segunda hipoteca tradicional que proporciona una cantidad fija de dinero en un solo desembolso inicial. A diferencia de un HELOC, donde los fondos pueden utilizarse a lo largo del tiempo, un HELOAN entrega el monto total del préstamo al momento del cierre y se paga mediante mensualidades fijas durante un plazo determinado. Muchos propietarios prefieren un HELOAN cuando saben exactamente cuánto dinero necesitan y quieren la tranquilidad de contar con un pago fijo y predecible. Si está financiando un proyecto importante de mejora de su vivienda con un presupuesto definido, pagando deudas con tasas de interés elevadas, comprando una propiedad de inversión o cubriendo un gasto grande de una sola vez, un HELOAN puede ofrecer certeza y estructura. Debido a que el monto del préstamo, el pago mensual y el calendario de pagos quedan establecidos desde el cierre, muchos prestatarios valoran la simplicidad de saber exactamente cuánto deberán pagar cada mes. No es necesario administrar diferentes retiros de fondos ni preocuparse por saldos fluctuantes. Para los propietarios que prefieren una solución de financiamiento sencilla y estructurada, un HELOAN puede ser una excelente opción. ¿Cuál Opción es Mejor? La respuesta depende de sus objetivos. Si necesita flexibilidad , quiere tener acceso continuo a fondos o espera que sus gastos ocurran a lo largo del tiempo, un HELOC puede ser la opción que mejor se adapte a sus necesidades. Si sabe exactamente cuánto dinero necesita y prefiere un pago fijo con un calendario de liquidación definido , un HELOAN puede ser una opción más conveniente. La buena noticia es que ambos productos pueden permitir a los propietarios acceder al capital acumulado en su vivienda sin modificar su primera hipoteca existente. Para los propietarios que aseguraron tasas hipotecarias históricamente bajas, esto puede representar una ventaja significativa frente a refinanciar el saldo total de su hipoteca a las tasas actuales del mercado. ¿Te gustaría saber qué opción es adecuada para ti? Para programar una cita con Garrick Werdmuller, Presidente y CEO de Fresh Home Loan Inc. , visite: https://freshhomeloan.com/schedule-a-meeting/ Garrick Werdmuller President & CEO Fresh Home Loan Inc. 510-282-5456 NMLS 242952 Diana Diaz Operations Manager 510-751-0303 customercare@freshomeloan.com Redes Sociales https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@FreshHomeLoan https://www.tiktok.com/@freshhomeloan Todas las aprobaciones de préstamos están sujetas a revisión y aprobación final por parte del prestamista. Los préstamos se consideran aprobados únicamente cuando se emiten por escrito y se cumplen todas las condiciones. Las tasas y productos pueden no estar disponibles para todos los prestatarios y están sujetos a cambios según las condiciones del mercado y los términos de bloqueo de tasa. Fresh Home Loan Inc. es un Mortgage Broker de Igualdad de Oportunidades en California. Esta compañía realiza actos que requieren licencia de bienes raíces. Fresh Home Loan, Inc. está licenciada por el California Department of Real Estate #02137513 | NMLS #2124104. #HELOC #HELOAN #PropietariosDeVivienda #ConsejosParaPropietarios #Hipotecas #FinanzasPersonales #FinanciamientoDeVivienda #AgenteInmobiliario #FreshHomeLoan #BienesRaices #ConstruccionDePatrimonio #AsesoriaHipotecaria #LibertadFinanciera
By Garrick Werdmuller • August 3, 2026
BAKERSFIELD, Calif. — Fresh Home Loan Inc., an Independent California mortgage brokerage, is proud to announce its expansion into Bakersfield, bringing homebuyers, homeowners, real estate professionals, and investors greater access to competitive financing solutions and personalized mortgage guidance. Unlike traditional banks that offer only their own loan products, Fresh Home Loan works with a network of wholesale lenders to help clients find financing that best fits their unique financial goals and circumstances. "We're excited to bring our independent mortgage brokerage model to Bakersfield," said Garrick Werdmuller, President and Broker of Record at Fresh Home Loan. "Every client has a different story, and having access to multiple lending partners allows us to explore more financing solutions than a single lender can typically provide." Fresh Home Loan offers a wide range of mortgage programs, including: Conventional, FHA, VA, and Jumbo financing First-time homebuyer programs Low down payment and zero down payment options for qualified borrowers Bank statement loans for self-employed borrowers DSCR investor loans ITIN financing Private money and bridge financing HELOCs and home equity solutions Construction and renovation financing Reverse mortgages The Bakersfield expansion also strengthens Fresh Home Loan's commitment to supporting the local real estate community. The company plans to host educational workshops, networking events, and marketing collaborations designed to help real estate professionals grow their businesses while providing valuable education to consumers throughout Kern County. Fresh Home Loan's mission is simple: provide honest advice, competitive loan options, fast communication, and exceptional customer service from application to closing. "Our goal isn't simply to close loans," Werdmuller added. "We want to become a trusted mortgage resource for families, Realtors, builders, and investors throughout Bakersfield and Central California." For more information about Fresh Home Loan or to schedule a complimentary mortgage consultation, visit FreshHomeLoan.com or contact the Bakersfield office. About Fresh Home Loan Inc. Fresh Home Loan Inc. is an independent California mortgage brokerage dedicated to helping clients achieve homeownership through education, personalized service, and access to a broad network of wholesale lending partners. Serving communities throughout California, Fresh Home Loan offers financing solutions for first-time buyers, move-up buyers, investors, and homeowners seeking to refinance or leverage their home equity. Garrick Werdmuller President CEO Fresh Home Loan Inc 510.282.5456 call/text NMLS 242952 www.FreshHomeLoan.com Socials: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@freshhomeloan-garrickwerdm316 All loan approvals are conditional and not guaranteed and subject to lender review of all information. Loan is conditionally approved when lender has issued approval in writing, but until all conditions are met, loan cannot be funded. Specified rates and [products may not be available to all borrowers. Rates subject to change according to market conditions and agreed upon lock times set by borrower. Fresh Home Loan Inc. is an Equal Opportunity Mortgage Broker in California. This licensee is performing acts for which a real estate license is required. Fresh Home Loan, Inc. is licensed by the California Department of Real Estate #02137513 NMLS # 2124104
By Garrick Werdmuller • August 3, 2026
"Wait... I didn't know that. Maybe I qualify." "Here's something most homebuyers don't know." "Every mortgage has a set of guidelines, whether it is conventional to Jumbo, FHA, VA, USDA, ITIN, Revers Mortgage, whatever – there is an investor that purchases that loan according to a set of guidelines.” "But many lenders and especially the big banks add something called 'overlays.' " "An overlay is simply an extra rule the bank creates to reduce its own risk." For example, maybe the loan program allows a 620 credit score—but that bank won't go below 680. Or maybe the program allows a higher debt-to-income ratio say 43% but the bank only goes to 38% —but the bank has a stricter limit." "As an independent mortgage broker, I work with multiple wholesale lenders." "If one lender has stricter overlays, another lender may follow the standard program guidelines more closely or offer a different program that fits your situation." "That doesn't mean every loan can be approved—but it does mean one 'no' isn't always the final answer." According to the CFPB: Consumer Financial Protection Bureau these are the 3 most common reasons a loan is denied and how we can help: 1. Income This is the #1 reason. Examples: Self-employed with large tax write-offs. Commission or bonus income that's difficult to document. Retirees living on assets. Real estate investors. 1099 contractors. Recently changed jobs. Many banks have more conservative debt to income ratio overlays, leaving the borrower qualify for less. They also may not have niche loans for self-employed borrowers who sometimes have trouble qualifying off tax returns. Often times, real estate investors have deductions on that make it difficult to cash flow on their returns. Independent mortgage brokers like Fresh Home Loan Inc. can often access lenders that accept: Bank statement loans Asset utilization/depletion DSCR loans for investors Alternative income documentation 2. Credit Every lender has different overlays. Examples: Credit score just below the bank's minimum. Limited credit history. Recent bankruptcy or foreclosure. A manual underwriting situation. One lender may decline the loan while another approves it under a different program. 3. The Property or Collateral The borrower may qualify, but the property doesn't. Examples: Non-warrantable condos Deferred maintenance Unique property Many times, large banks simply won't finance these situations, while Independent Mortgage brokers can. Unlike traditional banks that offer only their own loan products, Fresh Home Loan works with a network of wholesale lenders to help clients find financing that best fits their unique financial goals and circumstances. For more information: https://www.freshhomeloan.com/contact-us Call or text: 510.282.5456 Email: Garick@freshhomeloan.com Garrick Werdmuller President CEO Fresh Home Loan Inc 510.282.5456 call/text NMLS 242952 www.FreshHomeLoan.com Socials: https://www.facebook.com/freshhomeloan/ https://www.instagram.com/garrickwerdmuller/ https://www.linkedin.com/in/garrick-werdmuller-b044253/ https://www.youtube.com/@freshhomeloan-garrickwerdm316 All loan approvals are conditional and not guaranteed and subject to lender review of all information. Loan is conditionally approved when lender has issued approval in writing, but until all conditions are met, loan cannot be funded. Specified rates and [products may not be available to all borrowers. Rates subject to change according to market conditions and agreed upon lock times set by borrower. Fresh Home Loan Inc. is an Equal Opportunity Mortgage Broker in California. This licensee is performing acts for which a real estate license is required. Fresh Home Loan, Inc. is licensed by the California Department of Real Estate #02137513 NMLS # 2124104 #HomeLoans #MortgageTips #HomeBuying #FirstTimeHomeBuyer #Realtor #RealtorLife #MortgageBroker #Chase #WellsFargo
By Garrick Werdmuller • July 22, 2026
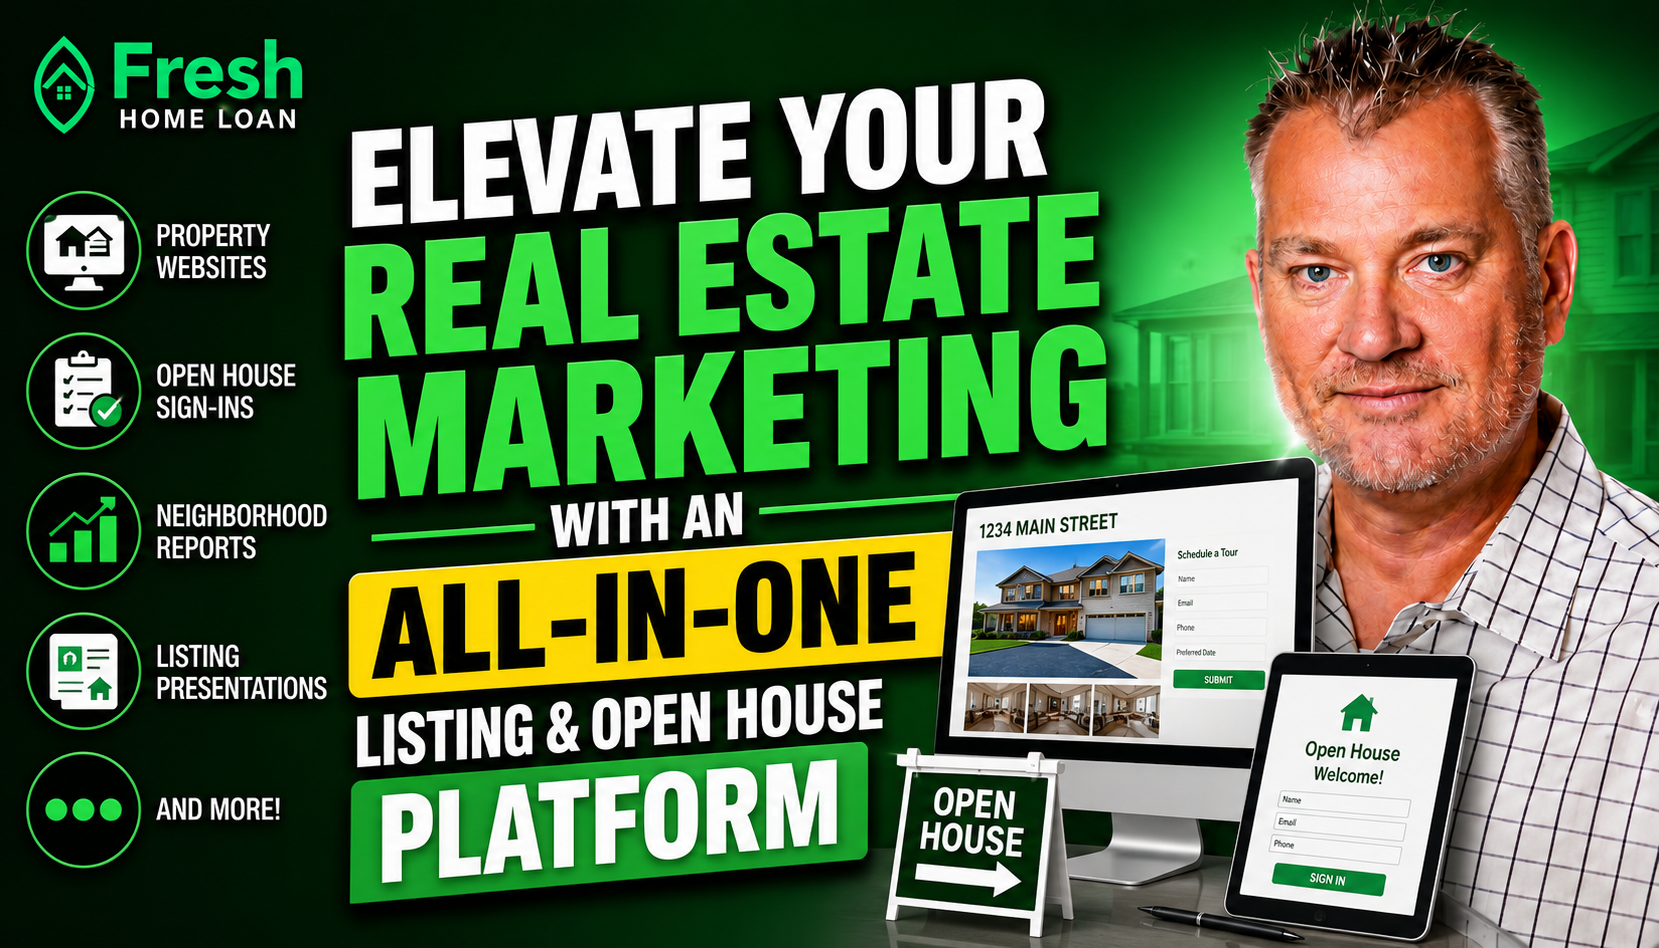
Thanks for visiting this page! I wanted to invite you to check out the system we're now using for our Open House marketing. I think it's a great opportunity for us to collaborate and help generate more leads together. It has a TON of features, including: 🏡 Property Websites Mobile-friendly listing websites Recently Sold property pages Lead capture tools Easy sharing on social media and email 🖨️ Print Marketing Open House Flyers Promotional Flyers Infographics Open House Sign-In Sheets Property Reports Jumbo Postcards Sign Riders 📢 Active Listing Marketing Coming Soon Flyers Just Listed Flyers Under Contract Flyers In Escrow Flyers Just Sold Flyers Go Green Flyers Property Reports and Marketing Pieces 📋 Listing Presentations Pre-Listing Presentations Neighborhood Reports Beautiful Infographics designed to help win listings 🏠 Buyer Resources Neighborhood Reports Buyer Infographics Market information to educate your clients 📬 Lead Generation Tools Sign Riders with lead capture Multiple postcard sizes and marketing campaigns Print and digital marketing working together Garrick Werdmuller President & CEO Fresh Home Loan, Inc. 🌐 https://freshhomeloan.com #ListingsToLeads #RealEstateMarketing #RealtorTools #ListingPresentation #OpenHouse #RealEstateLeads #MortgageBroker #FreshHomeLoan #RealtorSuccess #DigitalMarketing #RealEstateTechnology #LeadGeneration #RealEstateTraining #MarketingForRealtors